Introduction
ESOP for startups is one of those topics every founder thinks they understand until they’re actually structuring one — at which point it becomes clear that an ESOP sits at the intersection of three separate legal frameworks that rarely get explained together: company law governing how options are granted, tax law governing how they’re taxed at two completely different points, and the practical cap table mechanics of dilution and pool sizing. I advise founders on founder agreements and cap tables regularly, and ESOPs are the natural extension of that same conversation — get the structure wrong, and you either can’t legally grant what you promised, or your best hire owes a tax bill years before they see a rupee of actual liquidity. This guide covers ESOP for startups completely: the legal framework under the Companies Act, how to size and structure a pool, vesting and exercise price mechanics, the full tax treatment for both employer and employee, and a change in the 2025 Income Tax Act that most current guides on this topic still haven’t caught up to.
What Is an ESOP? The Four-Stage Lifecycle
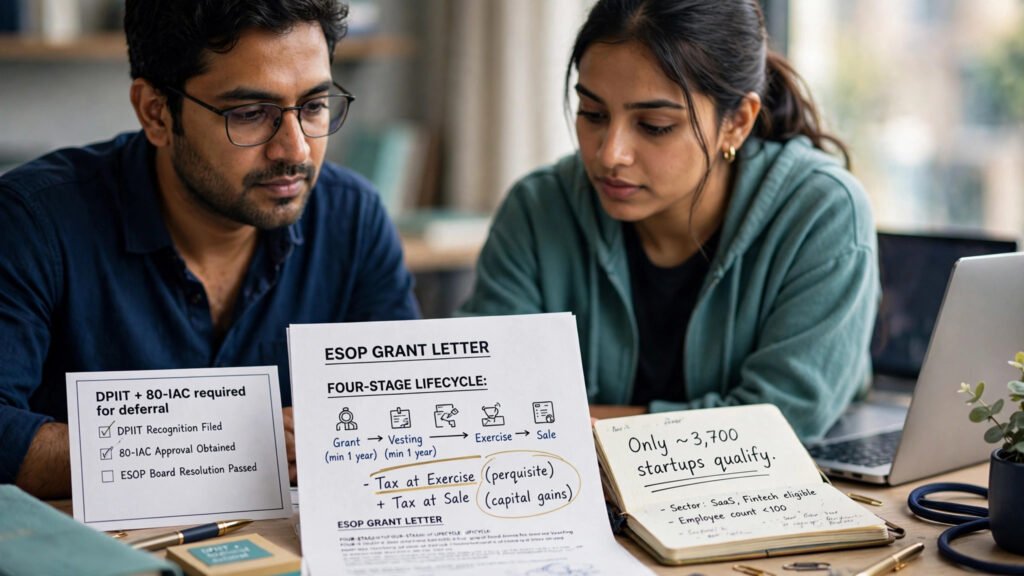
An Employee Stock Option Plan grants an employee the right, but not the obligation, to purchase company shares at a predetermined price after meeting specific conditions. Every ESOP for startups, regardless of company size or sector, moves through the same four stages:
- Grant — the company issues options to an employee, specifying quantity, exercise price, and the vesting schedule. No tax event occurs here; a grant is not taxable to the employee.
- Vesting — the employee earns the right to exercise options over time, subject to a mandatory minimum vesting period under Indian law (covered below). Until vesting, the employee has no actual entitlement to shares.
- Exercise — the employee pays the exercise price and receives actual shares. This is the first taxable event, taxed as a perquisite (salary income).
- Sale — the employee eventually sells the shares, triggering the second taxable event: capital gains.
The Legal Framework Behind Every ESOP for Startups
In India, the statutory authority for setting up an ESOP for startups comes from Section 62(1)(b) of the Companies Act, 2013, with the operational detail set out in Rule 12 of the Companies (Share Capital and Debentures) Rules, 2014. A few provisions here matter far more than most founders realize when structuring an ESOP for startups:
- Shareholder approval is required before any scheme can be implemented — a special resolution (75% majority) for public companies, though private companies can generally use an ordinary resolution under the MCA’s exemption notification, a meaningful compliance simplification most early-stage founders aren’t aware of.
- A mandatory minimum one-year vesting period applies between the grant date and the first vesting event, under Rule 12(6)(a). This is a statutory floor, not a design choice — options legally cannot vest any faster than this, regardless of what a founder might want to offer an exceptional early hire.
- Promoters and directors holding more than 10% equity are generally excluded from receiving ESOPs — but DPIIT-recognised startups get a specific relaxation from this restriction for 10 years from incorporation, which matters enormously for founder-promoters at early-stage companies who also want to participate in the option pool.
- Filing obligations include Form MGT-14 within 30 days of passing the special resolution, Form PAS-3 after share allotment upon exercise, and maintaining a Register of Employee Stock Options in Form SH-6.
Structuring the ESOP Pool for Startups: How Much and When
Most companies running an ESOP for startups size their pool between 5% and 15% of fully diluted equity, with 10% being a common landing point for companies planning multiple funding rounds. A few practical structuring decisions matter more than the exact percentage:
- Time the pool creation deliberately. Investors frequently require pool expansion as a condition of a priced round, and that expansion typically dilutes existing shareholders (including founders) rather than the incoming investor — a mechanic worth understanding before you’re negotiating a term sheet under time pressure.
- Decide between individual grants and an ESOP trust. Larger, more mature startups sometimes route options through a trust structure to simplify administration and buybacks, though for most early-stage companies, direct individual option agreements are simpler and sufficient.
- Reserve pool capacity for senior hires, rather than allocating the full pool immediately across the initial team, since later, more senior hires typically command meaningfully larger individual grants.
ESOP for Startups Vesting Schedules: The Standard vs. the Statutory Floor
The near-universal market standard when designing an ESOP for startups is a four-year vesting schedule with a one-year cliff — 25% vesting at the one-year mark, with the remaining 75% vesting monthly or quarterly over the following three years. This mirrors the founder vesting structure I recommend in the anatomy of a bulletproof founders agreement, and for good reason: both mechanisms exist to ensure equity is earned through sustained contribution, not granted upfront and walked away with. It’s important to distinguish this market convention from the legal minimum: Rule 12 only mandates a one-year gap between grant and the first vesting event — the full four-year structure is a contractual and market choice, not a statutory requirement, meaning founders retain real flexibility in structuring anything beyond that one-year floor.
Setting the Exercise Price
For any ESOP for startups, the exercise price is typically set at, or close to, the fair market value (FMV) of the shares on the date of grant. For unlisted companies — which describes almost every startup running an ESOP for startups — FMV must be determined by a Category I Merchant Banker, per Rule 3(8) and Rule 3(9)(ii) of the Income Tax Rules, 1962. This valuation matters twice over: it establishes the exercise price at grant, and it later becomes the reference point for calculating the perquisite tax at exercise, described next.
ESOP for Startups Taxation in India: The Two-Stage Model
This is where taxation for an ESOP for startups gets genuinely complicated, because it’s taxed twice, at two different points, under two different tax treatments:
Stage 1 — At Exercise (Perquisite Tax): The difference between the FMV on the exercise date and the exercise price the employee actually pays is taxed as a perquisite under Section 17(2)(vi) — treated as salary income, subject to TDS deducted by the employer, at the employee’s applicable slab rate.
Stage 2 — At Sale (Capital Gains Tax): When the employee eventually sells the shares, the FMV at exercise (already taxed as perquisite) becomes the cost of acquisition. The difference between the sale price and that cost basis is taxed as a capital gain — long-term or short-term depending on the holding period (12 months for listed shares, 24 months for unlisted shares), with long-term capital gains on listed shares currently taxed at 12.5% above a ₹1.25 lakh annual exemption threshold.
A worked example makes this concrete: an employee exercises options at an exercise price of ₹100 per share when FMV is ₹300 — a perquisite of ₹200 per share, taxed as salary. If those shares are later sold at ₹800, the capital gain is ₹500 per share (₹800 sale price minus the ₹300 FMV already taxed as perquisite), taxed under capital gains rules based on the holding period.
The DPIIT + Section 80-IAC Deferral: The Benefit Almost Everyone Describes Incorrectly
Here’s a critical correction that most content on how an ESOP for startups actually works gets wrong, and it matters enormously for cash-flow planning. The startup tax deferral under Section 192(1C) of the Income Tax Act does not apply to every DPIIT-recognised startup, despite how frequently that claim gets repeated. It applies only to startups holding both DPIIT recognition and an Inter-Ministerial Board (IMB) certificate under Section 80-IAC — and as of April 2026, only around 3,700 of India’s 1.97 lakh-plus DPIIT-recognised startups actually hold that second certification. If your startup has DPIIT recognition but not the 80-IAC IMB certificate, this deferral simply does not apply to your employees, and assuming otherwise is one of the most consequential and avoidable mistakes I see in ESOP for startups planning.
For genuinely eligible companies running an ESOP for startups program, the benefit is real and valuable: instead of TDS being deducted immediately at exercise, it’s deferred to the earliest of three trigger events — 48 months from the end of the assessment year in which shares were allotted, the date the employee sells the shares, or the date the employee leaves the company. The perquisite amount is still calculated and locked in at the exercise date; only the actual tax payment timing shifts.
The 2025 Update Most Guides Haven’t Caught Up To: 60 Months, Not 48
This is the change I’d flag first to any founder or employee researching ESOP for startups right now, because it’s recent enough that a large share of currently published content still gets it wrong. The Income Tax Act, 2025, effective from 1 April 2026, extends the deferral window from 48 months to 60 months under Section 392(3) read with Section 289(3) — a full year of additional breathing room. This extended window applies specifically to shares allotted on or after 1 April 2026; shares allotted before that date continue under the older 48-month rule set out in Section 192(1C) of the 1961 Act. For any startup planning ESOP grants around this transition date, the allotment timing itself now has a direct, material effect on how long employees can defer their perquisite tax liability — a planning consideration that simply didn’t exist before this year.
ESOP for Startups: What Happens If an Employee Leaves
Under a typical ESOP for startups scheme, vested options generally remain the employee’s to exercise within a defined post-termination window specified in the ESOP scheme (commonly 90 days, though this varies by company policy) — unvested options typically lapse immediately upon departure, reverting to the pool. For employees who already exercised under the DPIIT deferral described above, leaving the company is itself a trigger event: the full deferred perquisite tax becomes due, with TDS required to be deposited within 14 days of the separation date, regardless of whether the employee has any actual liquidity from those shares to fund that tax payment — a cash-flow trap worth planning around well before it happens.
ESOP vs. RSU vs. SAR vs. ESPP: How They Actually Compare
| ESOP | RSU | SAR (Cash-Settled) | ESPP | |
|---|---|---|---|---|
| Tax trigger | Exercise | Vesting/delivery | Payout | Exercise/purchase |
| Perquisite basis | FMV − exercise price | Full FMV (no exercise price) | Cash received (salary only) | FMV − discounted purchase price |
| Capital gains stage? | Yes, on sale | Yes, on sale | No — no shares held | Yes, on sale |
| DPIIT deferral available? | Yes | Yes (including sweat equity) | Not applicable | Case-by-case |
Common Mistakes With ESOP for Startups That Founders and Employees Make
- Assuming DPIIT recognition alone unlocks the tax deferral — as covered above, the 80-IAC IMB certification is a separate, much less common qualification.
- Granting options that vest faster than the one-year statutory floor, which simply isn’t legally possible under Rule 12, regardless of intent.
- Failing to properly document FMV through a Category I Merchant Banker for unlisted company grants, creating valuation disputes later.
- Not planning for the 14-day deferred tax trigger on exit, leaving departing employees with an unexpected tax bill and no liquidity to pay it.
- Treating the ESOP pool as founder-only dilution math, without considering that a properly structured pool, timed well, protects the cap table clarity investors expect during due diligence as much as it rewards employees.
- Forgetting to report ESOP income correctly on personal tax returns — perquisite income belongs in the salary schedule, and capital gains on eventual sale in the capital gains schedule, a distinction I’ve covered in more detail in how to file your ITR for the first time.
Conclusion: An ESOP for Startups Is a Legal Document Before It’s a Perk
Treating an ESOP for startups program as a simple recruiting perk — a number on an offer letter — is exactly how founders end up with a scheme that’s either non-compliant with Rule 12, structured around an incorrect assumption about the DPIIT tax deferral, or silent on what happens the day a valued employee actually leaves. Getting it right means engaging with all three layers at once: the Companies Act framework governing how options can legally be granted and vested, the genuinely two-stage tax treatment that follows the shares from exercise to sale, and the practical cap table mechanics of pool sizing and dilution. If you’re setting up an ESOP scheme for the first time, or reviewing one that’s already in place, you can reach out here, or explore more founder-focused legal and compliance guides on the blog.
Frequently Asked Questions (FAQ)
1. What exactly is an ESOP for startups, in simple terms? An ESOP for startups gives employees the right to buy company shares at a fixed price after meeting vesting conditions, allowing them to share in the company’s growth without the company having to pay higher upfront cash salaries.
2. What is the minimum vesting period for an ESOP in India? Under Rule 12(6)(a) of the Companies (Share Capital and Debentures) Rules, 2014, there must be a minimum gap of one year between the grant date and the first vesting event. The common four-year, one-year-cliff structure is a market convention, not a legal requirement beyond this one-year floor.
3. How is an ESOP taxed in India? ESOPs are taxed at two separate stages: as a perquisite (salary income) under Section 17(2)(vi) at the time of exercise, based on the difference between FMV and exercise price, and again as capital gains at the time of sale, based on the difference between the sale price and the FMV already taxed at exercise.
4. Does every DPIIT-recognised startup qualify for the ESOP tax deferral? No. The deferral under Section 192(1C) requires both DPIIT recognition and a separate Inter-Ministerial Board (IMB) certificate under Section 80-IAC. As of April 2026, only around 3,700 of over 1.97 lakh DPIIT-recognised startups hold this additional certification.
5. How long can eligible startup employees defer their ESOP perquisite tax? For shares allotted before 1 April 2026, the deferral runs until the earliest of 48 months from the end of the relevant assessment year, sale of the shares, or leaving the company. For shares allotted on or after 1 April 2026, the Income Tax Act, 2025 extends this window to 60 months.
6. What happens to ESOP tax if an employee resigns after exercising their options? Leaving the company is itself a trigger event under the deferral scheme. The full deferred perquisite tax becomes due, and the employer must deposit TDS within 14 days of the separation date, regardless of whether the employee has sold any shares.
7. How big should a startup’s ESOP pool be? Most Indian startups size their pool between 5% and 15% of fully diluted equity, with 10% being a common benchmark, though the right size depends on hiring plans, funding stage, and investor expectations for future rounds.
8. Who determines the exercise price for an ESOP in an unlisted startup? For unlisted companies, fair market value must be determined by a Category I Merchant Banker under Rule 3(8) and Rule 3(9)(ii) of the Income Tax Rules, 1962, and this valuation typically sets both the exercise price and the basis for calculating perquisite tax later.
9. Can startup founders and promoters receive ESOPs? Generally, promoters and directors holding more than 10% equity are excluded from receiving ESOPs under the Companies Act. However, DPIIT-recognised startups benefit from a specific relaxation of this restriction for 10 years from incorporation.
10. What is the difference between an ESOP and an RSU in terms of taxation? Both are taxed at two stages, but an ESOP’s perquisite is calculated as FMV minus the exercise price actually paid, while an RSU, which typically has no exercise price, is taxed on the full FMV at vesting or delivery as the perquisite.
11. Do unvested ESOP options survive an employee’s exit? No, typically not. Unvested options generally lapse immediately upon an employee’s departure and revert to the company’s option pool, while vested options usually remain exercisable within a defined post-termination window set out in the ESOP scheme.
12. Where should ESOP income be reported in an income tax return? Perquisite income from exercise should appear in the salary schedule (and typically reflects in Form 16, except where deferral applies), while capital gains from the eventual sale of shares are reported separately in the capital gains schedule of the ITR.