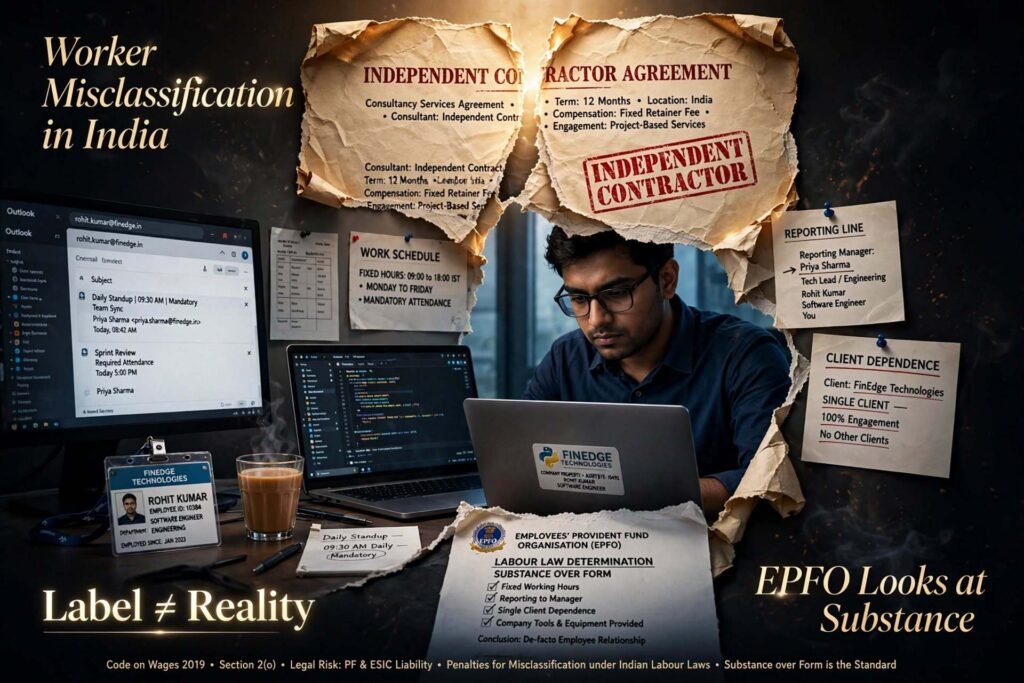
Worker misclassification in India is the quiet liability sitting inside a lot of foreign-company balance sheets right now. The pattern is familiar. A US or European startup finds a talented developer in Pune or Bengaluru, signs a short “independent contractor” agreement, pays an invoice every month through Wise or a similar platform, and calls it a day. No Indian entity, no payroll, no provident fund. It feels clean and cheap. Then the worker leaves, or an EPFO officer asks questions, and the company discovers that the contract title never decided anything. Indian authorities look at how the work is actually done, and if it looks like employment, the back-claims for EPF, ESI and gratuity can run to years. In this guide I’ll explain how the test works, what the 2025-26 labour code changes mean, what the exposure looks like in rupees, and how to structure the relationship properly. I’ll write it the way I’d talk a finance head through it, because for most companies this is a cost and risk question first and a legal one second.
What the “Consultant Trap” Actually Is
The consultant trap is the gap between what a contract says and what the relationship is. Foreign companies often route India hires through freelance agreements because it avoids setting up an entity and avoids statutory contributions on paper. Asanify’s 2026 research report on hiring in India calls this the “consultant trap” and links it to a wave of EPFO scrutiny, including the closing, on 30 April 2026, of an EPFO enrolment campaign that had let employers regularise unenrolled workers cheaply. I’d treat the report as a useful signal rather than gospel, since Asanify sells employer-of-record services, but the underlying legal risk is real and well documented in the law itself.
When a “Freelancer” Is Legally an Employee
Under the old EPF Act, Section 2(f) defined an employee as a person employed for wages in any kind of work, manual or otherwise, in or in connection with the work of an establishment, who gets wages directly or indirectly from the employer. Note how wide that is: the label doesn’t matter, and payment can come directly or indirectly. That Act has now been folded into the Code on Social Security, 2020, which came into force on 21 November 2025 and consolidates nine earlier social security laws, with the Social Security (Central) Rules, 2026 effective from 8 May 2026. The Code keeps an employee-based structure for provident fund, ESI and gratuity, and it adds categories like gig workers, platform workers and fixed-term employees. One point is easy to miss: recognition as a gig or platform worker does not by itself make someone an employee for EPF purposes, so a “gig” label is not a safe harbour either.
Indian courts have decided employment status for decades using a cluster of factors, going back to cases like Dharangadhara Chemical Works and Silver Jubilee Tailoring House, which developed the control test. In plain terms, authorities ask:
- Who controls how, when and where the work is done?
- Is the person integrated into the business, with a company email, team meetings, a reporting line and set hours?
- Is the person economically dependent on one client, or running their own practice with several?
- Who provides the tools, and who bears the financial risk?
- Can the person send a substitute, or must they personally perform the work?
- Is the engagement open-ended and full-time?
A developer who works fixed hours, reports to a manager, uses the company’s tools, serves one client for three years and can’t send a substitute is, in substance, an employee, whatever the contract says. A designer who delivers defined projects for five clients, invoices separately and sets her own schedule is much closer to a genuine contractor.
What Misclassification Costs: EPF, ESI and Gratuity
Once a relationship is treated as employment, the liabilities attach from the start of the engagement, not from the day of reclassification. The usual heads are:
- Provident fund. The employer’s contribution is 12% of wages, subject to the wage ceiling that applies to mandatory contributions. Interest and damages follow on unpaid periods. Vendor guides cite 12% a year interest and damages up to 100% of arrears under the older framework, so ask for a current confirmation of how these apply under the Code before you rely on that number.
- ESI. The employer’s share is 3.25% of wages, applicable to workers earning up to ₹21,000 a month. For well-paid tech workers this usually doesn’t bite, but it matters for lower-paid support, operations and sales roles.
- Gratuity. Normally payable after five years of continuous service, calculated at 15 days’ wages per year of service. The Code now gives fixed-term employees gratuity after one year, which makes short misclassified engagements more expensive than they used to be.
- Everything around it: leave, bonus where applicable, tax withholding on salary, and, in some structures, questions about whether the foreign company has created a taxable presence in India.
A simple illustration, with invented numbers. Suppose a developer is paid ₹1.5 lakh a month with basic wages of ₹75,000, for four years. Gratuity alone works out to roughly (75,000 × 15 ÷ 26) × 4, which is about ₹1.73 lakh, and that’s before provident fund arrears, interest, damages and the cost of dealing with an inquiry. Spread over a team of ten, the number stops being trivial. This is a rough sketch, not a calculation of your exposure, which depends on wage definitions, ceilings and dates.
There’s also a procedural point worth knowing. EPFO can inquire into coverage and dues, and employers who ignore notices end up with orders passed against them. The cheapest moment to fix a misclassification is before anyone has asked.
The Worker’s Side of the Story
If you’re the person who has been paid as a “consultant” for years, you’ve probably been missing provident fund savings, insurance cover and gratuity. You can raise the issue with the EPFO regional office or its grievance portal, and a genuine employment relationship can be established on the facts. Before you do, collect your evidence: the contract, the invoices, messages showing instructions and working hours, your company email, and any proof that you worked only for this one client. Be aware that claims against a foreign company without an Indian presence can be hard to enforce in practice, which is exactly why careful employers and workers both prefer to fix the structure early.
Why the Payment Channel Doesn’t Decide Anything
Paying through Wise, Payoneer or a foreign bank account doesn’t change the character of the relationship. It may make the payments less visible to Indian authorities for a while, but it doesn’t make them legitimate, and the worker’s bank records and tax filings tell the story eventually. If anything, a pattern of regular monthly payments of a fixed amount looks like a salary.
How to Structure a Compliant Engagement
There are four realistic routes, and the right one depends on the person, the duration and your plans in India.
1. A genuine independent contractor. This works when the engagement is project-based, outcome-driven, time-limited, and the person has other clients, uses their own tools and controls how they work. Put the facts in the contract and make sure the reality matches. A contract that says “independent” while the manager sets daily tasks is worse than useless, because it shows you knew the distinction mattered.
2. An employer of record (EOR). A local provider becomes the legal employer, runs payroll and statutory filings, and you direct the day-to-day work. It costs more per head than a contractor, but it removes the misclassification risk and the need for your own entity. Choose a provider carefully and read how liability is allocated in the agreement.
3. Your own Indian subsidiary. Sensible once you have a team of any size. You control hiring and culture, but you also take on incorporation, compliance, a resident director requirement and a bank account that can take weeks to open. If you’re weighing this, our guide on reverse flipping and redomiciliation covers the corporate structuring side of cross-border moves.
4. Direct employment, including fixed-term. Under the Code, a fixed-term employment contract is a legitimate option for defined-duration roles, with pro-rata benefits. It requires being registered as an employer, so it usually sits alongside an entity or an EOR.
Whichever route you pick, get the paperwork right. Written agreements should cover intellectual property assignment, confidentiality and, where relevant, non-solicitation, remembering that broad post-employment non-competes are generally unenforceable in India, as we explain in our piece on trade secret protection. If your team handles personal data of Indian users, your obligations under the DPDP framework follow the data, not the contract label. Our DPDP compliance guide covers what investors and regulators look for.
If You Already Have Misclassified Workers
Don’t panic and don’t ignore it. Start by listing every India-based contractor, how long they’ve worked for you and how they actually work. Sort them into genuine contractors and likely employees. For the second group, plan a move to employment through an EOR or entity, and take advice on whether and how to deal with past periods, because voluntary regularisation is usually cheaper than waiting for a notice. The EPFO enrolment campaign that closed in April 2026 shows the authorities were willing to offer a softer route for a time, but that window has reportedly closed, so assume the full regime applies now. If you’d like a structured review of your India hiring set-up, you can reach out here.
Frequently Asked Questions
1. Can a foreign company hire an Indian freelancer without an Indian entity?
Yes, if the person is a genuine independent contractor delivering services. The risk arises when the arrangement is really employment.
2. What decides whether someone is an employee in India?
The substance of the relationship: control, integration into the business, economic dependence, tools, risk and exclusivity. The contract title is not decisive.
3. Does paying through Wise or Payoneer make it a contractor relationship?
No. The payment method has no bearing on legal status.
4. What liabilities arise if a contractor is reclassified?
Provident fund contributions, ESI where applicable, gratuity, interest and damages on arrears, and potentially tax-related consequences, usually calculated from the start of the engagement.
5. Did the Code on Social Security replace the EPF Act?
Yes. The Code came into force on 21 November 2025 and consolidates nine earlier social security laws, including the EPF Act, with the 2026 Central Rules effective from 8 May 2026.
6. Are gig and platform workers automatically covered by EPF?
No. Recognition as a gig or platform worker does not by itself make someone an employee for EPF purposes. The Code provides for separate social security schemes for them.
7. Is gratuity payable to short-term employees now?
Fixed-term employees are entitled to gratuity under the Code after one year of service, calculated pro rata, which is more generous than the older five-year rule.
8. What is an employer of record?
A local company that legally employs your staff in India, handles payroll and statutory compliance, while you direct the work.
9. Can the worker claim these benefits later?
Yes. A worker who was in substance an employee can raise the issue with the EPFO and other authorities, supported by evidence of how the work was done.
10. What should I do if I already have misclassified workers?
Audit the relationships, move genuine employees to a compliant structure, and take advice on how to handle past periods before authorities raise the issue.
Conclusion
The consultant trap works only until someone looks closely. Indian law cares about what the relationship is, not what it’s called, and the costs of getting it wrong accumulate quietly for years before they show up. If you’re hiring in India, decide up front whether you want a contractor, an EOR, an entity or a direct employee, and make the facts match the paper. The extra cost of doing it properly is almost always lower than the back-claims, interest and distraction of doing it later.
This article is general information, not legal or tax advice for your specific arrangements. Statutory rates, ceilings and the application of Code provisions should be confirmed with a qualified professional.