On 8 October 2026 the 57th GST Council did something founders have asked for since 2017. It recommended scrapping GST arrest powers altogether by omitting Section 69 of the CGST Act. It also recommended lifting the prosecution threshold from ₹1 crore to ₹5 crore, narrowing the offences listed in Section 132(1), and cutting the general penalty from ₹25,000 to ₹10,000.
Read the headlines and you would think the matter is closed. It is not. Those are recommendations. Until Parliament amends the CGST Act, and every state legislature amends its own GST law, the GST arrest power in Section 69 still works exactly as it did on 7 October. If you have a summons on your desk or an audit running, the Council’s press release will not help you in front of an officer.
This guide does three things. It explains what can lead to GST arrest today, what the proposed changes would and would not do, and what a founder should put on file now, so that if a GST problem ever lands, you can show good faith with documents and not with promises.
What the 57th GST Council actually recommended on GST arrest provisions
The official press release is short and specific. These are the criminal-side points:
| Area | Today | Recommended on 8 October 2026 |
|---|---|---|
| GST arrest | Commissioner can authorise arrest under Section 69 | “Complete withdrawal” by omitting Section 69 |
| Prosecution threshold | ₹1 crore | ₹5 crore |
| Section 132(1) offences | Clauses (a) to (l) as they stand | Clause (i) dropped; “evades tax” removed from (e); “or in any other manner deals with” removed from (h); (c) limited to ITC claimed without receipt of goods or services or without an invoice |
| Punishment | Fixed bands, with a six-month minimum in Section 132(3) | “Rationalised”, with imprisonment or fine or both, according to one analysis of the proposal |
| General penalty (Section 125) | Up to ₹25,000 | Up to ₹10,000 |
The same meeting also recommended a 5% reduced penalty in non-fraud cases if tax and interest are paid within 30 days of a Section 73 order or 60 days of a Section 74A order, removal of the ₹10,000 minimum penalty in non-fraud cases, no show cause notice where the tax involved is below ₹10,000, a ₹40 crore cap on pre-deposit for penalty-only orders, and a rule that goods interception on the road should happen only on specific intelligence.
The proposal to scrap GST arrest provisions is a genuine shift in tone. It is also a list of intentions.
A recommendation on GST arrest is not law
This is the part founders skip, and it is the part that gets people hurt. The Council’s own press release says its recommendations “would be given effect through the relevant circulars/ notifications/ law amendments which alone shall have the force of law.” The release carries no effective date for the GST arrest, prosecution or penalty changes. Some other items do have dates, such as refund changes for ITC availed from 1 November 2026, but the criminal provisions do not.
Here is what has to happen before GST arrest relief protects you:
- A Bill amends the CGST Act. One analysis expects it could come in the Winter Session, but no date is announced and the final wording may differ from what was reported.
- Every state amends its SGST Act. GST is a dual law. If a state lags, the officers of that state work under the old text.
- A commencement notification fixes the date. The Act can come into force on one day for some sections and another day for others.
- A savings clause decides what happens to old matters. This is where pending cases are won or lost.
On that last point, one analysis argues that withdrawing the GST arrest power should apply to pending matters from the day it commences, since a withdrawn procedural power cannot be used for past conduct, though arrests made earlier on valid grounds would stand. For lighter punishment, it points to the Supreme Court’s reasoning in T. Barai v. Henry Ah Hoe that an accused who has not yet been sentenced can claim the benefit of a milder penalty. The higher threshold is the contested part. Section 6 of the General Clauses Act can preserve pending prosecutions, and the Council expressly said the new ₹10,000 show cause notice threshold applies to pending notices but said nothing comparable about prosecutions. If the Bill repeats that silence, a court may read it as deliberate. That is one author’s view, not settled law, but it is a good reason not to plan around retrospective relief.
The lesson that goes beyond GST
The same discipline applies to almost every piece of regulatory news a founder reads.
- A press release is not a notification. Look for the gazette.
- A draft rule or consultation paper is a request for comments, not a rule.
- A notified Act can still sit idle until a commencement date. Always check it.
- A savings clause tells you whether your old facts live under the old law.
We made this point on DPIIT recognition too: the change that matters is the notified one, not the headline. Our guide to DPIIT startup recognition 2026 shows what a notified rule looks like next to a news report about it.
When can GST arrest actually happen today?
Strip away the fear and the position is narrower than most founders assume.
The power. The GST arrest power in Section 69 lets the Commissioner authorise arrest if he has “reasons to believe” that a person has committed an offence under Section 132(1)(a) to (d). Those are broadly supplying goods or services without an invoice, issuing an invoice without any supply, taking or using input tax credit without receipt of goods or services, and collecting tax from customers but not paying it over. The arrested person must be produced before a Magistrate within 24 hours.
The money threshold. Only the highest band, where tax evaded, ITC wrongly availed or refund wrongly taken exceeds ₹5 crore, makes those offences cognizable and non-bailable. Lower bands carry lesser consequences and are generally bailable. One analysis tabulates today’s punishments as up to one year for ₹1 to 2 crore, up to three years for ₹2 to 5 crore, and up to five years above ₹5 crore.
What the Supreme Court has said. In Radhika Agarwal v. Union of India (February 2025), the Court upheld Sections 69 and 70 and rejected the argument that arrest powers fall outside the GST Act. It also added limits that matter in practice. The Commissioner must form an opinion based on material and record it in writing. Arrest cannot be used to find out whether the conditions for arrest exist. And a payment provision cannot be enforced through coercion or the threat of arrest. CBIC Instruction 01/2025-GST requires the grounds of arrest to be given in writing, and CBIC Circular 01/2022-23 addresses coercive recovery before adjudication.
Anticipatory bail against GST arrest. The same decision confirms that where there is a specific and credible apprehension of arrest, you can approach the court for anticipatory bail even before an FIR exists.
Summons come first. Most founders meet GST enforcement through a summons under Section 70, not a knock at midnight, and a summons usually comes long before any GST arrest. A statement you give there can be used later, and what you sign matters more than what you say in the corridor.
Directors and companies. Exposure to GST arrest and prosecution is not limited to the person who signed the invoice. Where a company commits an offence under the Act, Section 137 can reach the persons in charge of its business. If you are a director who also signs returns or approves ITC, assume your name is on the file.
If GST arrest is removed: what shifts and what stays
| Likely to ease | Likely to remain |
|---|---|
| GST arrest power under Section 69 goes | Tax, interest and civil penalties stay recoverable |
| Cases under ₹5 crore fall out of criminal prosecution | Prosecution before a criminal court on a complaint stays possible above the threshold |
| Fewer offence clauses, with the catch-all wording gone | Fake invoice and fraudulent ITC offences stay |
| Court discretion on sentence (imprisonment, fine or both) | Summons, search, seizure and attachment powers stay |
| Lower general penalty | Other laws, such as PMLA and Customs, keep their own arrest powers |
Three cautions on GST arrest reform. Paying tax, interest or penalty does not automatically end an existing criminal complaint. Compounding is not available to someone accused under Section 132(1)(b) after the 2023 amendment. And one analysis warns that if Section 132(5) is not amended in step with Section 69, ordinary police arrest procedure could still be argued to apply. Wait for the text.
If you have a summons, audit or investigation running
Do not treat the Council’s decision as a shield. Until the law changes, GST arrest remains possible on the facts described above. Do the following this week.
- Read the document in front of you. A summons under Section 70, an audit intimation and a show cause notice are three different things with different deadlines.
- Get a lawyer and a chartered accountant into the room before the first statement. Statements are evidence. Read every page before signing and keep a copy.
- Do not pay under pressure to make a problem go away. Recovery needs notice and an adjudication order under Section 79. Voluntary deposits can be made, but make them deliberately, with a covering letter that records the reason and your reservation of rights.
- Reconcile before you reply. Match GSTR-1, GSTR-3B, GSTR-2B and the books. Most replies fail on numbers that do not tie.
- Preserve everything. Do not delete emails, chats, invoices or vendor files. Deleting a record after a summons turns a tax dispute into something worse.
- If GST arrest is a real worry, speak to criminal counsel about anticipatory bail early. The remedy is available on a credible apprehension, and waiting until the officers arrive is too late.
- Track the legislation. If a Bill is introduced, read its commencement and savings clauses. They decide whether your pending matter benefits.
The good-faith file: what every founder should assemble now
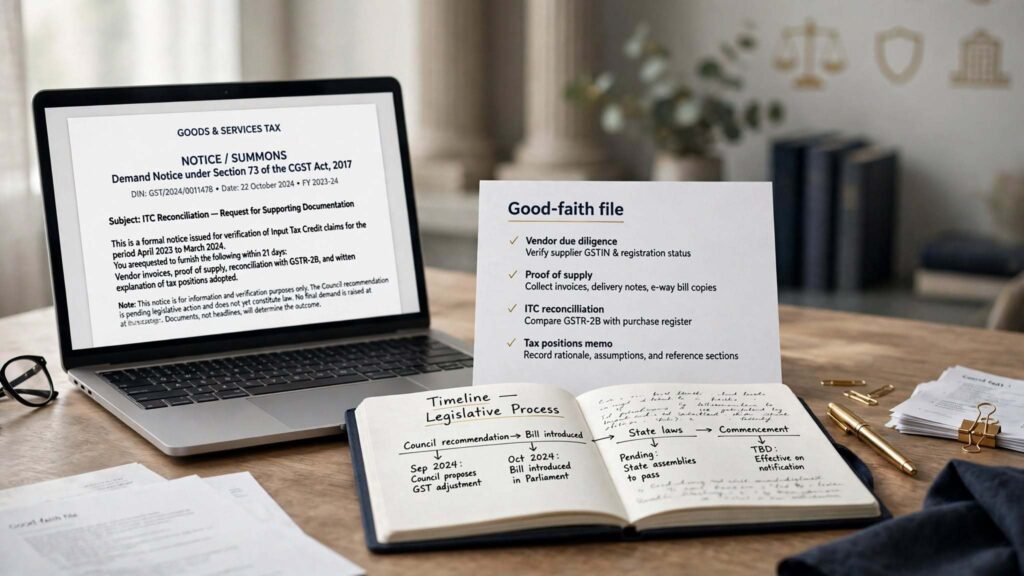
If an officer ever alleges fake ITC or short payment, and GST arrest is on the table, the question in the room is often one of intent. Did the company know, or should it have known? Documents answer that better than assurances. Build this file before you need it.
| Control | What to keep | Why it matters |
|---|---|---|
| Vendor due diligence | GST registration check, return filing history, PAN and address proof, a short onboarding note | Shows you did not take a supplier on trust |
| Proof of actual supply | Purchase order, delivery challan, e-way bill, transport receipt, goods received note, service work logs | Fake-invoice cases turn on whether goods or services really moved |
| Payment trail | Bank transfers to the supplier’s own account, no cash or third-party payments | A payment through banking channels supports genuineness |
| ITC register | Monthly reconciliation of books with GSTR-2B, with reasons for any ITC held back | Shows a working process, not a hurried scramble |
| Tax positions memo | A short note, backed by a professional opinion, on every aggressive interpretation (classification, place of supply, exemption) | Separates a bona fide dispute from suppression |
| Authority matrix | Who files returns, who approves ITC, who holds login credentials and DSC, who answers notices | Avoids a single point of blame |
| Notice and summons log | Date received, deadline, responsible person, reply sent, outcome | Missed dates create the worst cases |
| Board visibility | A quarterly GST compliance note placed before the board or the partners | Evidences oversight at the top |
| Document retention | A written policy for how long invoices, e-way bills and reconciliations are kept | Records disappearing is read against you |
None of this is exotic. A founder who can hand an officer a clean vendor file and a reconciliation on day one is in a different position from one who has to rebuild it after a summons.
If you are still setting up the basics, our legal checklist for Indian startups and the guides on Startup India registration and MSME registration cover the registrations that sit alongside GST. For contracts with vendors, the clauses that matter here, such as audit rights, tax-compliance warranties and indemnity for ITC loss, are explained in our contract law glossary.
Why this sits in a bigger pattern
The Council’s move on GST arrest follows the government’s wider push to stop treating small business mistakes as crimes. We covered the same instinct in the Jan Vishwas Act 2026. The mistake to avoid is reading a pro-business direction as permission to relax. Criminal exposure also lives in places founders forget, such as dishonoured cheques (see our guide to the cheque bounce notice) and personal guarantees (see the personal guarantor trap). Treat the Council’s decision as a reason to tidy your records, not to stop keeping them.
If you want a second pair of eyes on your vendor contracts, compliance policies or a notice you have received, you can get in touch, and the startup legal section lists related guides.
What to watch next
- Whether a CGST amendment Bill appears in the Winter Session, and how it words commencement and savings.
- Whether state legislatures amend their SGST Acts at the same pace.
- Whether Section 132(5) and the bail provisions are amended alongside Section 69.
- The exact punishment bands once the text appears.
- Any CBIC instruction on handling pending summons and investigations in the meantime.
Until then, GST arrest is a live power with live safeguards.
Frequently asked questions
1. Has GST arrest been abolished?
No. The 57th GST Council recommended on 8 October 2026 that Section 69 be omitted, but a recommendation does not change the Act. Parliament has to amend the CGST Act, each state has to amend its own GST law, and a commencement notification has to fix the date. Until then, the GST arrest power in Section 69 stays in force.
2. When can GST arrest happen today?
When the Commissioner has recorded reasons to believe that an offence under Section 132(1)(a) to (d) has been committed, and authorises the arrest in writing. The Supreme Court’s Radhika Agarwal decision (February 2025) says that belief must rest on material, and arrest cannot be used merely to investigate. The arrested person has to be produced before a Magistrate within 24 hours.
3. Which GST offences are non-bailable?
Offences under Section 132(1)(a) to (d), where the tax evaded, ITC wrongly availed or refund wrongly taken is above ₹5 crore, are cognizable and non-bailable under the current Act. Lower bands are generally bailable. The Council’s proposal would raise the prosecution threshold to ₹5 crore, so the picture will change only after enactment.
4. Does the ₹5 crore prosecution threshold apply to pending cases?
Nobody can say yet. The Council’s release is silent on pending prosecutions, while it expressly applied the new ₹10,000 show cause notice threshold to pending notices. One analysis argues that arrest withdrawal and lighter punishment should help pending matters, while the higher threshold is contested under Section 6 of the General Clauses Act. The savings clause in the final Bill will decide it.
5. Can I get anticipatory bail against GST arrest?
Yes, where you have a specific and credible apprehension of arrest, even before an FIR is registered. The Supreme Court’s 2025 decision upholding the arrest power also confirmed that route. Speak to criminal counsel early, because an application is far stronger before the officers act than after.
6. What happens if I ignore a GST summons?
Ignoring a Section 70 summons risks escalation, including penal consequences for non-attendance and a harder look at your file. Attend through your advisers, answer what is asked, read the statement before signing and keep a copy. If the date is impossible, write and ask for another one, with reasons.
7. Are directors personally liable for GST offences?
They can be, and that includes exposure to GST arrest in serious cases. Under Section 137 of the CGST Act, persons in charge of a company’s business at the time of an offence can be proceeded against, subject to the statute’s defences. Directors who approve ITC, sign returns or hold filing credentials should keep records showing what they reviewed and relied on.
8. Will fake invoice and ITC fraud cases still be prosecuted if GST arrest goes?
Yes. The Council kept the core offence of issuing invoices without supply and claiming ITC without receipt of goods or services. Prosecution through a criminal court on a complaint, tax recovery, penalties, search, seizure and attachment all stay in the framework. Other laws also keep their own arrest powers.
9. Does paying the tax and interest end a criminal case?
Not automatically. Payment helps on the civil side and may be relevant to sentence, but an existing criminal complaint does not disappear because the demand is paid. Compounding is also not available to a person accused under Section 132(1)(b) after the 2023 amendment.
10. What should I do right now to protect my business from GST arrest and prosecution?
Reconcile your GST returns with your books, build a vendor due diligence file, keep proof of supply and payment for every ITC claim, write down your tax positions with professional opinions, set an authority matrix for who files and who answers notices, and log every notice and summons with its deadline. If you have a live matter, get legal and tax advisers in before you reply.
This article is general information, not legal or tax advice. The 57th GST Council decisions are recommendations as of 26 October 2026 and the enacted text may differ. Confirm the current position with a qualified lawyer or chartered accountant before acting.
Sources: GST Council, Recommendations of the 57th Meeting (press release); TaxGuru, 57th GST Council’s Arrest and Prosecution Reforms: Do They Apply to Pending Cases?; TaxGuru, Key Reforms in GST Prosecution, Penalties and Demand Proceedings; TaxGuru, Should GST Arrest Powers Be Abolished?; CAclubindia, Section 132 Prosecution Changes and Withdrawal of GST Arrest Powers; EY, SC upholds the constitutional validity of power to arrest under Customs and GST law.