In February 2026, Rajya Sabha MP Raghav Chadha said out loud what Indian crypto founders had been muttering for four years. The state taxes virtual digital assets like a perfectly legitimate asset class, and then treats them, on the regulatory side, as if they barely exist. He posted his numbers on X the next day, along with a line that stuck: “Prohibition is not protection.”
Those numbers, and I want to be clear they are his and not the government’s: around 12 crore Indians trading on overseas platforms, ₹4.8 lakh crore of trading volume moved offshore, 73% of Indian volume sitting on foreign exchanges, and roughly 180 Indian crypto startups relocated abroad. He also argued that a proper domestic framework could add ₹15,000–20,000 crore a year in tax.
It is now late October. The speech has left the news cycle. The VDA paradox has not left the statute book. If anything, crypto regulation in India has become heavier on compliance without becoming any clearer on legal status, and that is the exact problem a founder has to build around. This guide covers what the law says today, what changed after February, which of Chadha’s figures hold up, and what a founder should actually do about it.
What is the VDA paradox, in plain words?
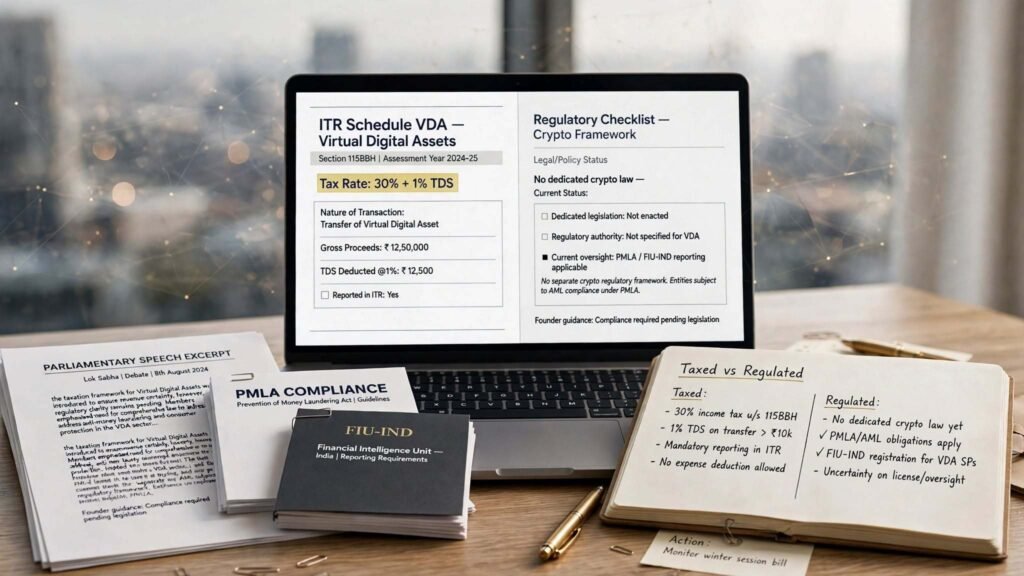
“Virtual digital asset” (VDA) is the tax-law label for crypto-assets, NFTs and similar tokens. The Income Tax Act, 2025, in force from 1 April 2026, kept the regime and now names “crypto-asset” explicitly in the definition. The paradox is the gap between what the state collects and what it provides:
| What the state does | What the state does not do |
|---|---|
| Charges a flat 30% crypto tax in India on gains | Recognise VDAs as an asset class in a dedicated law |
| Deducts 1% TDS on transfers under Section 194S | Run a licensing regime for exchanges |
| Makes you disclose in Schedule VDA of your ITR | Offer investor protection or a grievance forum |
| Treats VDA businesses as reporting entities under the PMLA | Set rules on custody, market conduct or stablecoins |
Crypto is not legal tender. Buying, selling and holding it is lawful. The Supreme Court struck down the RBI’s 2018 banking ban in 2020, and the country has lived in this uneasy middle ever since. The finance minister’s reported line is that taxing something does not make it legal, and the government told the Lok Sabha in July 2025 that the sector is unregulated. Both statements are accurate. That is exactly the complaint.
The tax side: harsh, simple and enforced
If you only remember one section of this article, make it this one. The tax rules are the part of crypto regulation in India that is fully written down, and the part the department actually enforces.
- Rate: a flat 30% on gains, plus 4% cess and any surcharge, under the Section 115BBH regime. Holding period and income slab are irrelevant. Even if your total income is below the basic exemption limit, VDA gains are still taxed at 30%.
- Deductions: only the cost of acquisition. Gas fees, exchange fees and your internet bill do not count.
- Losses: a loss cannot be set off against salary, business income, shares or even another crypto gain, and it cannot be carried forward.
- TDS: 1% under Section 194S on the transfer consideration, with a threshold of ₹10,000 for most people and ₹50,000 for specified persons.
- Gifts, airdrops, staking: gifted VDAs are taxed at fair market value in the recipient’s hands. Staking, mining and airdrop income is still treated unevenly, so keep records and ask your CA.
- Reporting: Schedule VDA in ITR-2 or ITR-3. The sale consideration you report should not be lower than the gross receipts shown against Section 194S TDS in Form 26AS, or you risk a defective-return notice under Section 139(9).
A quick example. You make ₹50,000 profit on token A and lose ₹50,000 on token B in the same year. You might expect a nil tax bill. You owe tax on the ₹50,000 gain: 30% is ₹15,000, plus 4% cess of ₹600, so ₹15,600. The loss on token B simply evaporates.
Crypto regulation in India: more rules than people realise, still no crypto law
Outsiders assume nothing governs this sector. Wrong. India does regulate crypto businesses, through anti-money-laundering plumbing instead of a purpose-built statute.
- PMLA since March 2023. VDA service providers are reporting entities. The obligation is activity-based, which means an offshore exchange serving Indian users is covered even without an Indian office. The notified activities are exchange between VDAs and fiat, exchange between VDAs, transfer of VDAs, safekeeping or administration, and participation in financial services linked to an issuer’s offer and sale of a VDA.
- FIU-IND registration brings KYC, record-keeping and suspicious-transaction reporting. Law firm guides put the process at roughly two to three months. FIU-IND also updated its compliance guidelines for crypto entities in January 2026.
- Enforcement is real. On 9 September 2026, FIU-IND issued notices and takedown directions to 15 unregistered offshore VDA service providers.
- Budget 2026 (1 February). Rates and TDS were left alone. A new reporting regime under Section 509 of the Income-tax Act, 2025, with penalties under Section 446 of ₹200 a day for non-filing and ₹50,000 for inaccurate statements, applies to prescribed reporting entities from 1 April 2026. It lines up with the OECD’s crypto-asset reporting framework.
- CBDT notification of 5 March 2026, as reported, pulled crypto-assets into India’s FATCA/CRS-style reporting.
The catch is that registration is not approval. FIU-IND tells you an exchange knows who its customers are. Nobody checks whether it holds your coins safely, prices fairly or can survive a bad month. That is the investor-protection gap Chadha was pointing at.
Are the headline numbers actually solid?
Founders quote them constantly, so it’s worth a pause.
The 12 crore figure is in the same range as the Chainalysis adoption estimates, which put India around 119 million users. But a different number came out of the RBI’s submission to Parliament, as reported by Economic Times: about 3.93 crore KYC-verified users across 54 FIU-registered providers, holding roughly ₹20,437 crore. These measure different things. One counts people who touch crypto anywhere. The other counts people verified on registered platforms.
The 73% offshore share and the ₹4.8 lakh crore figure were presented in Parliament and I could not trace either to a published dataset. The ₹15,000–20,000 crore revenue figure is a projection, not a measurement. Treat all of them as advocacy numbers: directionally plausible, not audited. If you are writing a pitch deck or a policy note, cite them as Chadha’s claims.
What has happened since February
- 1 Feb: Budget keeps 30% and 1% intact, adds reporting penalties.
- 9–10 Feb: Chadha’s Rajya Sabha speech and X post.
- 5 Mar: CBDT crypto-asset reporting notification.
- 1 Apr: Income Tax Act, 2025 takes effect.
- July: the RBI tells the parliamentary panel that a prohibition-leaning containment approach stays on the table and urges that banks and private stablecoins stay apart, according to reports.
- August: a hearing with the Department of Economic Affairs is cancelled. The long-promised government discussion paper on crypto has reportedly been shelved repeatedly since May 2025.
- 9 Sep: FIU-IND action against 15 offshore platforms.
- 16 Sep: the Standing Committee on Finance wraps up its year-long VDA inquiry. Its chair, Bhartruhari Mahtab, reportedly described the government’s stance as neither accepting VDAs nor regulating them. A successor committee takes over in October.
So no new law, no discussion paper, a tougher enforcement posture, and a committee reshuffle. That is the honest summary of crypto regulation in India after eight months.
Both sides of the argument
The reform case. Chadha and much of the industry say prohibition does not stop trading, it only moves it. A regulatory sandbox with real AML guardrails would bring volume and talent back onshore, protect retail users and widen the tax base. The relocation of exchange founders to Dubai and Singapore over the past few years is the usual exhibit.
The cautious case. The RBI’s worry is financial stability and monetary sovereignty, with private stablecoins at the centre. It has also argued that formal regulation could give speculative assets a false stamp of safety. The government’s own position is that tax and legitimacy are separate questions. Those are serious arguments, and they come from the institutions that would carry the risk.
Both camps agree that today’s arrangement is untidy. They disagree on whether “tidy” means a framework or a ban.
What founders must do, depending on what you build
If you run a VDA service (exchange, custody, transfers, token services)
Assume FIU-IND registration applies to you. Founders who think their product is too niche to be a “VDA service provider” are often wrong, because the notified activities are broader than “exchange”. Sort the corporate structure first, then register, then build KYC and transaction monitoring that actually works. Our legal checklist for Indian startups covers the basics you need in place before any funding conversation.
If crypto is only a payment rail or a treasury asset
You are mostly in tax territory. Platform and service fees are generally charged 18% GST. If you pay a vendor or contractor in tokens, that can be a taxable transfer for them and can create TDS duties on your side, so have it checked before you send the first payment. Also note that DPIIT recognition and its tax holiday are aimed at business income, and VDA gains stay at 30%. Read our guides on Startup India registration and the 2026 DPIIT recognition rules before you build tax assumptions into a model.
If you are thinking of leaving
Dubai, Singapore and Malaysia are the usual destinations. Moving the company does not delete the Indian exposure. FIU-IND rules follow the activity, so serving Indian users keeps you in scope. Founders who stay Indian tax residents still carry personal tax and reporting duties. Effective management and control questions, overseas investment rules under FEMA, and GST on services to Indian customers all need advice before you move, not after. A relocation is a legal project, not a flight booking.
Contracts and structure: the unglamorous layer that decides outcomes
In a grey zone, paper does the work that regulation does elsewhere. These are the spots where disputes usually start:
- Terms of service. Say plainly that the asset is not legal tender, that returns are not promised and who holds custody. Understand the difference between Terms of Service and a Privacy Policy before copying a template.
- Data. Wallet addresses, KYC files and transaction histories are personal data. Investors now test this in diligence, as we explain in DPDP compliance and VC due diligence and in our note on DPDP contract clauses.
- Token deals. If you raised on a token promise or an equity-plus-token side letter, get the instruments reviewed. The contract law glossary explains terms like SAFE and term sheet in plain language.
- Founder equity. Illiquid, volatile tokens and vesting do not mix well with aggressive forfeiture clauses. See the bad leaver clause before you sign.
- Personal guarantees. Banks that will touch a crypto business often ask for them. The personal guarantor trap shows what that can cost you.
If you want a second pair of eyes on any of these, the startup legal section is where I keep the relevant guides, and you can reach out directly.
A founder’s checklist for the rest of 2026
- Work out whether you are a VDA service provider. If yes, register with FIU-IND before anything else.
- Reconcile every Schedule VDA entry with Form 26AS before filing.
- Keep cost-of-acquisition records for every token, including swaps. Fees will not help you, but the purchase price will.
- Do not plan around loss set-off. It does not exist.
- Check GST on every fee line you charge.
- Get token payments to vendors and staff reviewed for TDS before they happen.
- Put a “not legal tender, no guaranteed returns” disclosure in your terms and onboarding.
- If you plan to relocate, get tax, FEMA and PMLA advice in one conversation instead of three.
- Test a banking fallback. UPI inflows linked to peer-to-peer crypto sales have been frozen in unrelated investigations, and the new Finance Committee is expected to look at it.
What to watch next
Four things. The successor Standing Committee on Finance, which forms this month. The Department of Economic Affairs discussion paper, if it ever gets published. The RBI’s line on stablecoins. And FIU-IND enforcement against offshore platforms, which has been the one reliably active front. I would not plan a business around a crypto law arriving in 2026.
Frequently asked questions
1. Is crypto legal in India in 2026? (Crypto regulation in India, short version)
Crypto is not banned, and you can legally buy, sell and hold it. It is also not legal tender and has no dedicated statute recognising it as an asset class. Parliament has been told the sector is unregulated, while tax and anti-money-laundering rules apply in full. “Legal to hold, heavily taxed, lightly protected” is the accurate description.
2. What does “the VDA paradox” mean?
It is the argument that India taxes virtual digital assets at a flat 30% with 1% TDS, which treats them as legitimate, while offering no legal recognition, licensing law or investor protection. Raghav Chadha summed it up in Parliament in February 2026 as taxing them like legal assets and regulating them like illegal ones.
3. How is crypto taxed in India?
Gains are taxed at a flat 30% plus 4% cess and surcharge, regardless of holding period. Only the purchase cost is deductible. A 1% TDS applies on transfers above the threshold, and everything is reported in Schedule VDA of your ITR. Business income from running a VDA platform is taxed separately at normal business rates.
4. Can I set off crypto losses against other income?
No. A VDA loss cannot be set off against salary, business income, capital gains on shares or property, or gains on another token. It also cannot be carried forward. That is why a trader with equal profit and loss in the same year can still owe tax.
5. Did Budget 2026 or the Income Tax Act, 2025 change crypto taxation?
The rates and TDS stayed the same. What changed is reporting. The new Act, in force from 1 April 2026, names “crypto-asset” in the VDA definition, and Sections 509 and 446 introduced a reporting regime for exchanges with penalties of ₹200 a day for non-filing and ₹50,000 for inaccurate statements.
6. Does my crypto startup need FIU-IND registration?
If you carry out any of the notified VDA activities for Indian users, the answer is generally yes. That includes exchanges, transfers, custody and services around token issuance. The rule is activity-based, so being incorporated abroad does not exempt you, and FIU-IND has already acted against unregistered offshore platforms.
7. Does moving to Dubai or Singapore solve the problem?
It solves some problems and creates others. You gain a clearer licensing regime. You do not escape FIU-IND rules if you serve Indian users, and Indian-resident founders keep personal tax duties. Corporate residence questions, FEMA rules and GST on services also need advice up front.
8. Are stablecoins treated differently from other crypto?
Not under tax law. They sit inside the VDA framework and get the same 30% and 1% treatment. Regulatory policy is a separate fight. The RBI has argued for keeping private stablecoins away from regulated financial channels, while the government has at times looked at a framework of its own.
9. Will India pass a crypto law soon?
There is no timetable. The government’s discussion paper has reportedly been delayed repeatedly, the RBI remains sceptical, and the parliamentary committee hand-over is happening in October. Planning around new crypto regulation in India arriving in the next few months would be optimistic.
10. What should a crypto founder fix first?
Three things in order: work out whether you need FIU-IND registration, get your tax reporting and TDS reconciliation clean, and tighten your contracts and policies. Terms of service, privacy policy, founder agreement and investor paperwork are where disputes start, and they are cheap to fix early.
This article is general information, not legal or tax advice. Rules and numbers change, so confirm the current position with a qualified lawyer or chartered accountant before acting.
Sources: Raghav Chadha’s X post (10 Feb 2026); BusinessToday; MediaNama; CAalley; Outlook Business; CryptoTimes (Aug and Sep 2026 reports); Cyril Amarchand Mangaldas FIG paper on VDA regulation; Treelife and CMS guides on FIU-IND and PMLA; TaxGuru and CAclubindia on Budget 2026 Sections 509 and 446; Analytics Insight and Patron Accounting on Income Tax Act, 2025; Inc42 on FIU-IND notices; cryptoinfrastructure.io regulation tracker (October 2026).